A reconstruction contractor’s insurance is built on general liability with completed operations, because the rebuild stays standing in the customer’s building after the crew leaves. Workers compensation, equipment and materials coverage, subcontractor certificates, and professional liability then follow from how the rebuild is staffed, scoped, and sold.
Why rebuild work changes the program
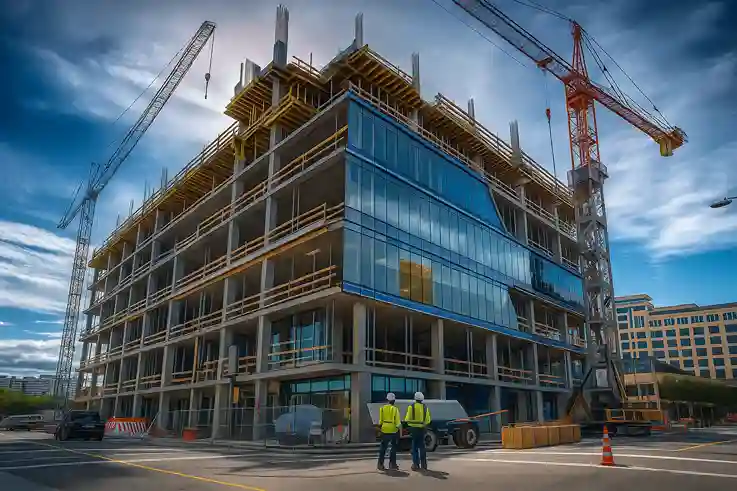
Mitigation and reconstruction are two different businesses that happen to follow each other. Mitigation is fast, short-lived, and ends when the building is dry or clear. Reconstruction is slower, schedule-driven, subcontracted, and permanent: what you build is still there when the claim arrives.
Insurers read the two differently. A mitigation company is a response fleet with a pollution question. A reconstruction company is a construction company, with the exposures that implies: subcontractors, materials, trades coordinating in one space, and a long tail. When a restoration company adds rebuild work, the program written for the first business does not automatically fit the second, a point we develop in How to Grow a Restoration Company Without Outgrowing Your Insurance.
General liability and completed operations: the claim after you leave
The central exposure of reconstruction is the one that arrives after you have been paid. A finished repair can fail, leak, burn, or injure someone months or years later, and the question becomes whether your policy responds. That is completed operations, the portion of general liability that answers injury or damage arising from your finished work.
Read how the form defines “your work,” and whether exclusions narrow what responds when the work was performed by a subcontractor. Ask also how long the coverage remains responsive. We devote a full post to this in Completed Operations: The Claim That Arrives After You Leave, and it is the most important sentence in the program for any contractor who rebuilds.
Three questions are worth putting to whoever places your coverage. Does the form respond to damage to the work itself, or only to damage the work causes to other property? Do exclusions for faulty workmanship or for subcontracted work narrow what answers? And how does the policy treat a claim made long after the job, once the policy year in which you did the work has ended? The answers differ by form, and the difference is usually invisible on a certificate.
Subcontractors and the certificate chain
Rebuild work is staffed by trades: framers, drywall, flooring, paint, electrical, plumbing. Most reconstruction contractors subcontract a share of it, and every subcontract is an insurance decision. If a sub is uninsured or underinsured and something goes wrong, the claim tends to return to the general contractor.
The discipline is simple and rarely complete. Require written agreements. Collect certificates before work starts. Read them for the right lines, not only for the existence of a policy. Keep them current across the length of the job. And tell the person placing your coverage how much of the work you subcontract, because that number changes how the program is read. A certificate is a starting point; the forms behind it decide what actually responds.
Older materials and the rules that come with them
Rebuild work often follows demolition, and demolition in older buildings can disturb materials nobody expected. Two federal rules are worth knowing exist, without treating this post as a legal guide. EPA’s Renovation, Repair and Painting Rule requires that anyone paid to perform work that disturbs painted surfaces in covered older housing, childcare facilities, and preschools be certified, with workers trained in lead-safe work practices; the details are on EPA’s lead renovation, repair and painting program page. For larger buildings, EPA’s asbestos rule calls for a thorough inspection before renovation or demolition and notification to the delegated entity, as described in its overview of the asbestos NESHAP.
The insurance consequence is the same in both: disturbing those materials is a pollution exposure, and it is the kind general liability excludes. Whether your rebuild work touches them is a question to answer by job, and contractors pollution liability is the line to read against it. Confirm which rules apply to your jobs with the source, since scope and exemptions vary.
The scope the carrier approves is not the contract you signed
Reconstruction after a loss has an unusual feature: two documents describe the same work. One is the carrier’s scope of repair, which sets what the funding party will pay for. The other is your agreement with the property owner, which sets what you promised to build. They are supposed to match, and on a long rebuild they drift. Supplements are requested, conditions are discovered behind walls, upgrades are asked for, and the schedule moves.
That drift is a business problem before it is an insurance problem, and it becomes an insurance problem when a dispute over what was promised turns into an allegation about the work. Written change orders, dated photographs, and a clean record of what was approved and by whom are the practical defense. They also make your underwriter’s job easier, because a contractor who documents scope changes is one whose completed-operations exposure can be understood. A contractor who keeps that paper straight is arguing from a stronger position if scope is ever questioned.
Workers compensation and auto on a construction schedule
A rebuild changes the crew as much as the claim. Carpenters, finishers, and laborers work at heights, with power tools, and in structures that may not yet have working utilities. Workers compensation classifications for construction work differ from those for emergency response, so confirm that the payroll described to the carrier reflects the rebuild crew and not only the mitigation crew.
The fleet changes too. Trucks that once carried drying equipment now carry lumber, tools, and debris, and make daily trips rather than emergency runs. Tell the person placing your coverage how vehicle use has shifted, since a schedule-driven fleet and a response fleet are not underwritten the same way.
Materials, tools, and work in progress
A rebuild job puts materials on site, in storage, and in transit. Lumber, cabinets, flooring, and fixtures are purchased before they are installed, and the question of who carries the risk while they wait depends on the contract. Sometimes the structure being rebuilt is insured by the property owner’s arrangement; sometimes the contractor is asked to provide coverage; and materials stored off-site or moving between locations are a separate matter, usually answered by an installation or equipment floater. Your tools and equipment are covered under contractors equipment if the form is written for property away from your premises.
Read the agreement before the first delivery. A materials loss on a Friday is a bad time to learn whose policy was supposed to respond.
Professional liability where you scope, design, or manage
Some reconstruction contractors do more than build. They write the scope, manage the project, make code-driven decisions, or offer design-build services. Where the allegation can be that the plan was wrong rather than that the work was careless, professional liability matters, because a claim built on a wrong judgment may be excluded from general liability. Ask honestly how much of your work is decision-making and how much is installation.
Real-World Scenario: A restoration company that has done mitigation for years takes on its first full rebuild after a fire, using a framing sub and a flooring sub. The job closes and the invoice is paid. Months later, a water intrusion at a repaired wall is traced to a sub’s work, and the property owner’s carrier looks to the contractor. The sub’s certificate lists general liability, but nobody read it, and the company’s own policy had been written for response work. The rebuild was good enough to pass inspection. The program was not built for the timeline it created.
What changes when you add rebuild to a mitigation company
The honest summary is that adding reconstruction adds a second company inside the first. The classification changes, the subcontractor exposure arrives, the tail of completed operations opens, and the paperwork multiplies. How Do Restoration Companies Make Money? Revenue Streams Explained describes why owners add the stream; this post is about what the program has to do once they do.
Tell the person placing your coverage before the first rebuild contract, describe the work and the subcontracting honestly, and ask how the program will treat it. The restoration contractor insurance page describes how we build for companies that do both, and you can ask for a quote review before your first rebuild contract is signed.
Sources
- EPA, Lead Renovation, Repair and Painting Program — EPA’s statement that anyone paid to perform work that disturbs painted surfaces in covered older housing, childcare facilities, and preschools must be certified and their employees trained. It addresses certification, not insurance. epa.gov/lead
- EPA, Overview of the Asbestos NESHAP — EPA’s description of inspection and notification requirements for renovation and demolition of covered buildings. It addresses regulation, not insurance. epa.gov/asbestos